- 0
- 211 words
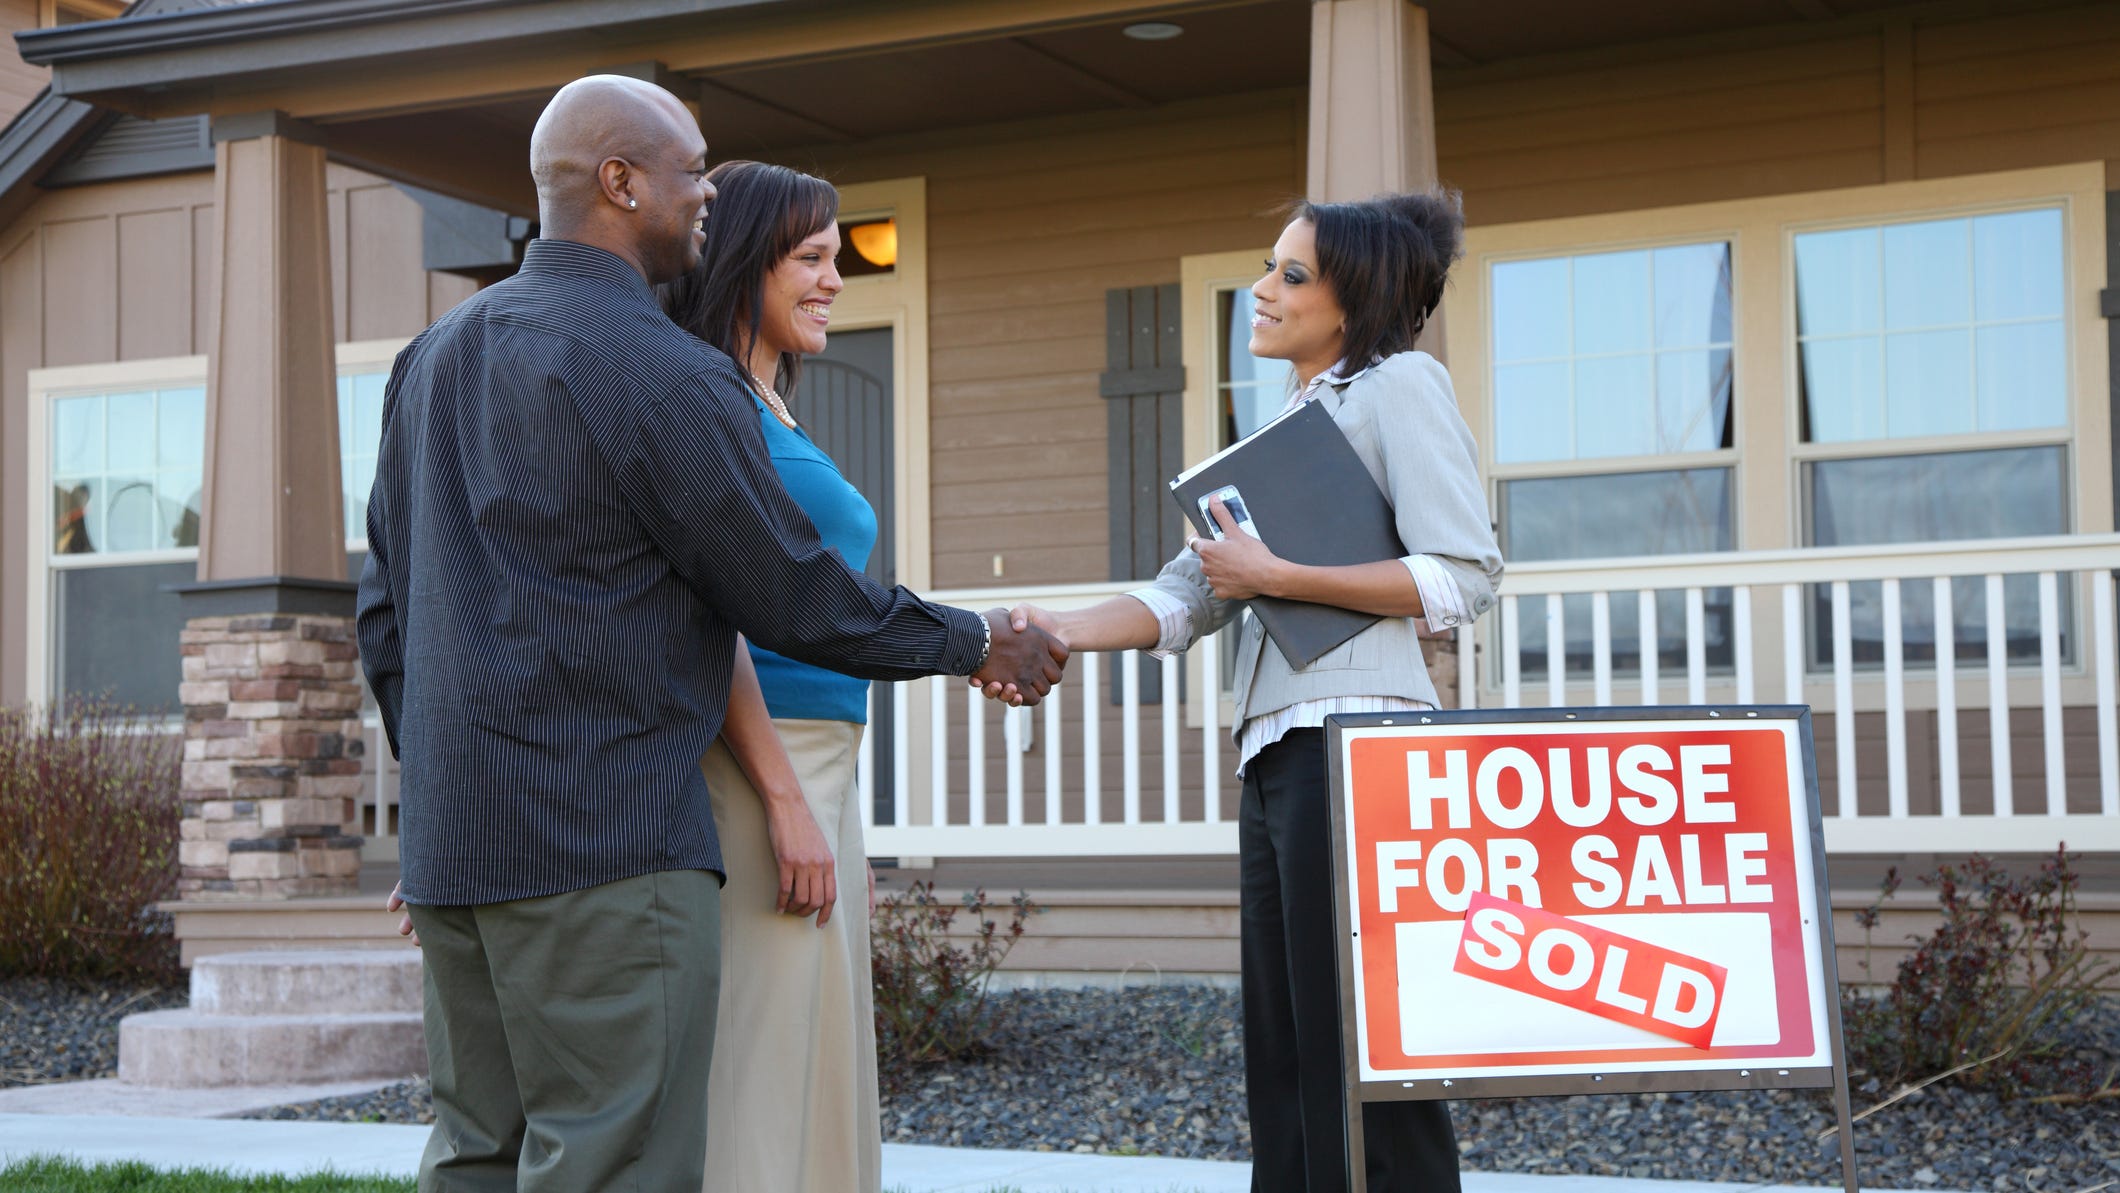
FHA loans can make homeownership more accessible for buyers with limited savings or less-than-perfect credit. These government-backed mortgages reduces lenders' risk by providing federal insurance on qualifying loans for borrowers who may not otherwise qualify.
\n\nWhile FHA loans can help secure home financing with a lower down payment and reduced credit requirements than conventional mortgages, they also include mortgage insurance costs and other restrictions buyers should understand. Learning what an FHA loan is and how it works can help you determine whether this type of financing fits your homebuying goals.
\n\nAn FHA loan is a mortgage that's insured by the Federal Housing Administration, which is part of the U.S. Department of Housing and Urban Development (HUD). Because the FHA insures the loan against losses when borrowers fail to pay, lenders can be more flexible regarding credit and down payment requirements than they might otherwise be.
\n\n"FHA loans give people with a 580 credit score an opportunity to only put 3.5% down. It is one of the most accessible loan products,” explains Ashley Harris, Director of Homebuyer Education at Neighbors Bank.
\n\nThe federal government doesn't directly lend the money for FHA loans. Homebuyers still apply to private lenders, such as banks…
Original source: https://www.usatoday.com/money/
Author

seoexperts1994@gmail.com
Related Posts

Even the smallest joys can help prevent suicide, researchers say
- 0
- 209 words
September 22, 2026 / 1:06 PM EDT / CBS News New research is shedding light on suicide prevention strategies, highlighting that even...
Read out all
Bone density and the “silent disease”: 4 things women should know about bone health
- 0
- 211 words
September 23, 2026 / 7:00 AM EDT / CBS News Seven out of 10 American women will have osteopenia or osteoporosis in...
Read out all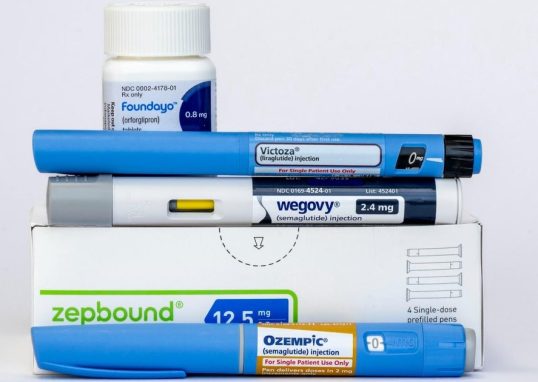
Will an FDA crackdown curb access to cheaper GLP-1 weight-loss drugs? Here’s what to know.
- 0
- 206 words
September 24, 2026 / 11:53 AM EDT / CBS News The Food and Drug Administration has warned a major compounding pharmacy that...
Read out all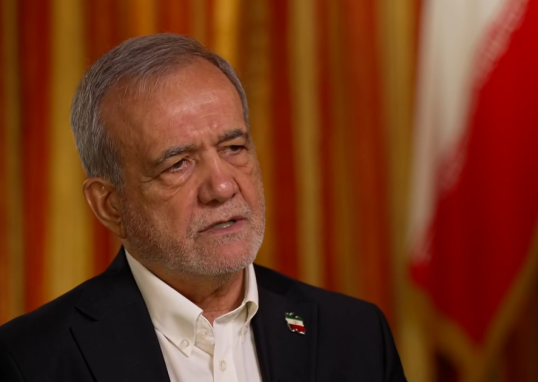
Iranian President Masoud Pezeshkian talks about proposal to reopen Strait of Hormuz, says Iran would allow nuclear inspectors
- 0
- 214 words
Updated on: September 26, 2026 / 12:13 PM EDT / CBS News Iranian President Masoud Pezeshkian said there was an "atmosphere of...
Read out all
Teen’s headache reveals alarming health risk for family: “Saving people’s lives”
- 0
- 213 words
September 26, 2026 / 8:00 AM EDT / CBS News Caroline McCaffrey usually ran in the morning, but on Father's Day 2025,...
Read out all
Transcript: Iranian President Masoud Pezeshkian on “Face the Nation with Margaret Brennan”
- 0
- 206 words
September 25, 2026 / 9:10 PM EDT / CBS News The following is the transcript of the interview with Iranian President Masoud...
Read out all