- 0
- 214 words
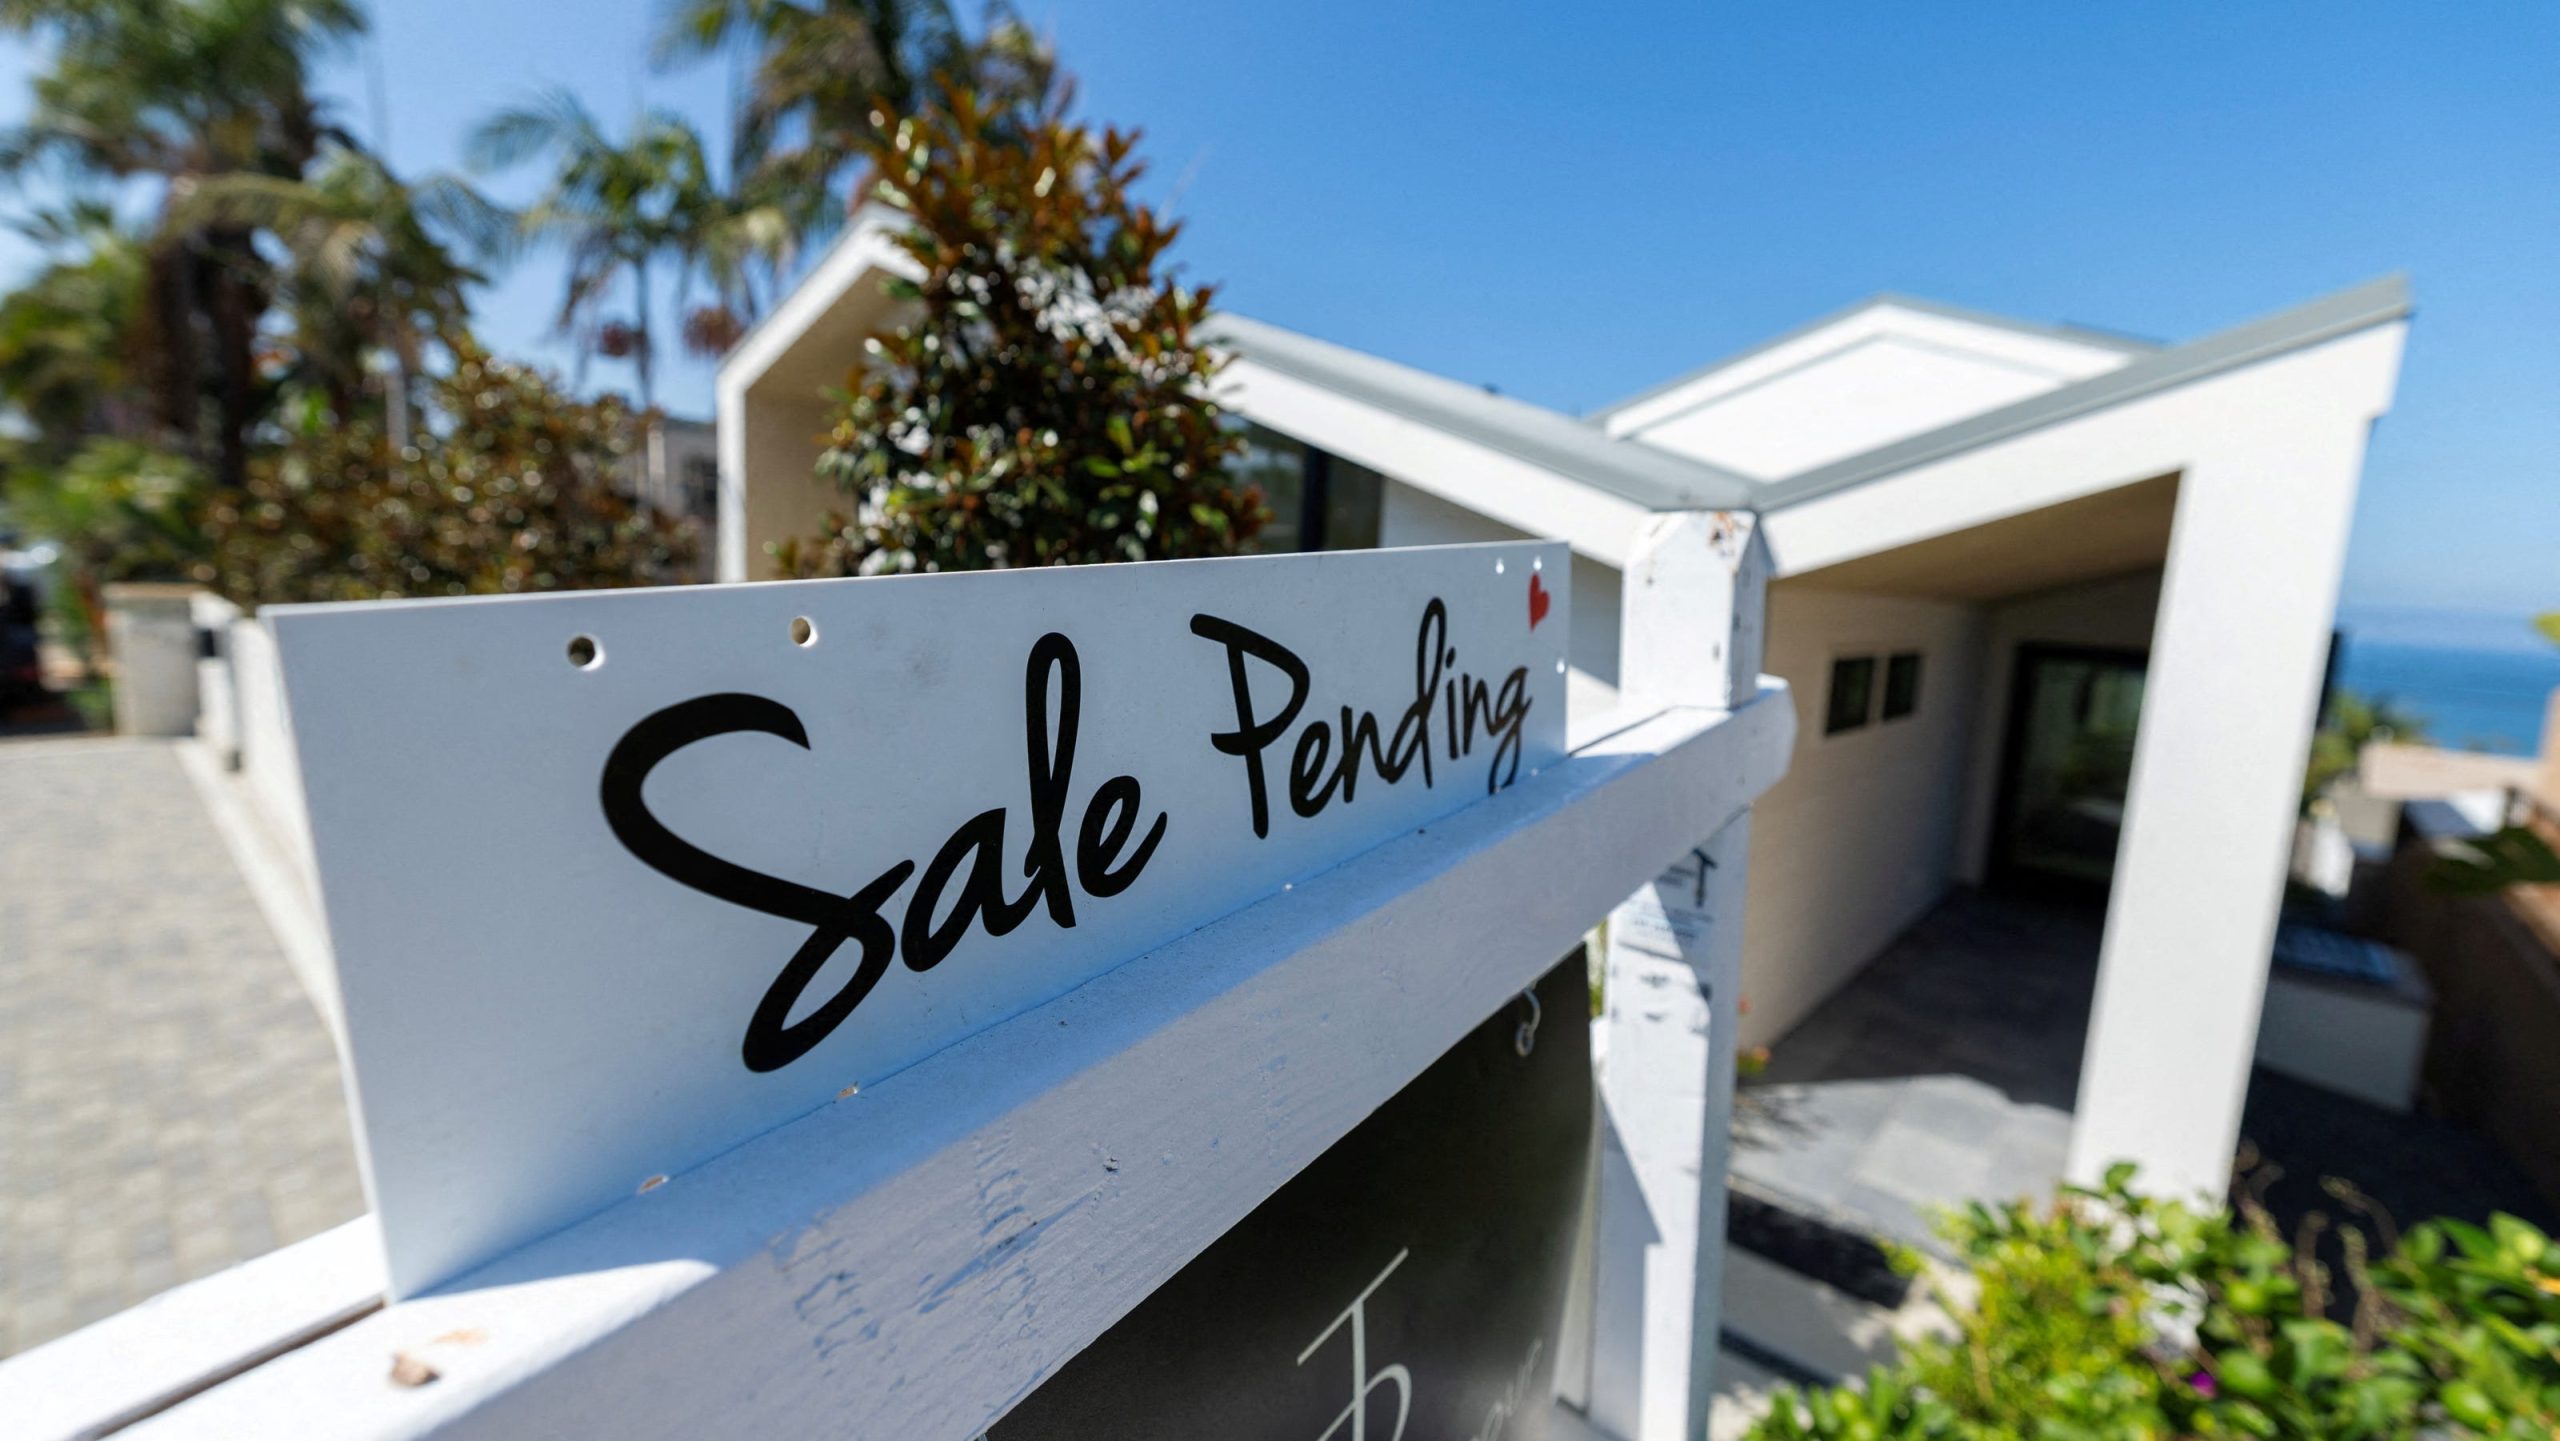
Homebuyers face higher borrowing costs after the 30-year fixed rate for mortgages rose last week to its highest level in nearly two years.
\n\nDon’t just blame the Federal Reserve.
\n\nWhile it’s true that Fed policymakers on Sept. 16 raised their benchmark for short-term interest rates to combat stubborn inflation, that doesn’t mean they also raised mortgage rates.
\n\nThe federal funds rate stands at a range of 3.75% to 4%, a quarter percentage point higher than before. That’s generally good news for savers and bad news for borrowers. But unlike high-yield savings yields or credit card APRs, which respond to changes in the Fed’s target range, home loan rates and the federal funds rate are loosely linked.
\n\nThe Fed does not set mortgage rates. The 30-year fixed rate for mortgages, for example, tends to follow the yield on the 10-year Treasury note. Still, the Fed can influence mortgage rates indirectly if its policy decisions move Treasury yields.
\n\n"While I don't expect one Fed meeting to change the housing market overnight, what matters now for Americans is whether their entire financial picture starts to feel more manageable," Mike Miedler, Century 21 Real Estate's president and CEO, said in a note. "Families are…
Original source: https://www.usatoday.com/money/
Author

seoexperts1994@gmail.com
Related Posts
Environmental groups sue Trump administration over rollback of vehicle mileage rules
- 0
- 204 words
Updated on: October 2, 2026 / 4:45 PM EDT / MoneyWatch Environmental groups filed a lawsuit on Friday against the Trump administration...
Read out all
American Airlines will let travelers mix cash and miles to pay for flights
- 0
- 209 words
Updated on: October 2, 2026 / 3:20 PM EDT / CBS News American Airlines customers will soon be able to mix cash...
Read out all
Amazon vows $1 billion for data center towns, warning U.S. “can’t afford to lose” AI race
- 0
- 208 words
October 2, 2026 / 1:42 PM EDT / CBS News Amazon's cloud computing division on Friday announced a new effort to temper...
Read out all
Amazon Prime customers could get $200 refunds in expanded FTC deal. See who is eligible.
- 0
- 192 words
October 2, 2026 / 10:44 AM EDT / CBS News Amazon is issuing refunds to eligible Amazon customers under a revised $2.5...
Read out all
OpenAI parts ways with 3 researchers it says mishandled sensitive information
- 0
- 211 words
Updated on: October 1, 2026 / 2:04 PM EDT / CBS News OpenAI has parted ways with three employees who the company...
Read out all
9 in 10 Americans have encountered a cyber scam as AI fuels fraud, Consumer Reports finds
- 0
- 206 words
Updated on: October 1, 2026 / 3:50 PM EDT / MoneyWatch Digital fraud is skyrocketing due to artificial intelligence, which is boosting...
Read out all